Industry
Accounting for Cultivators
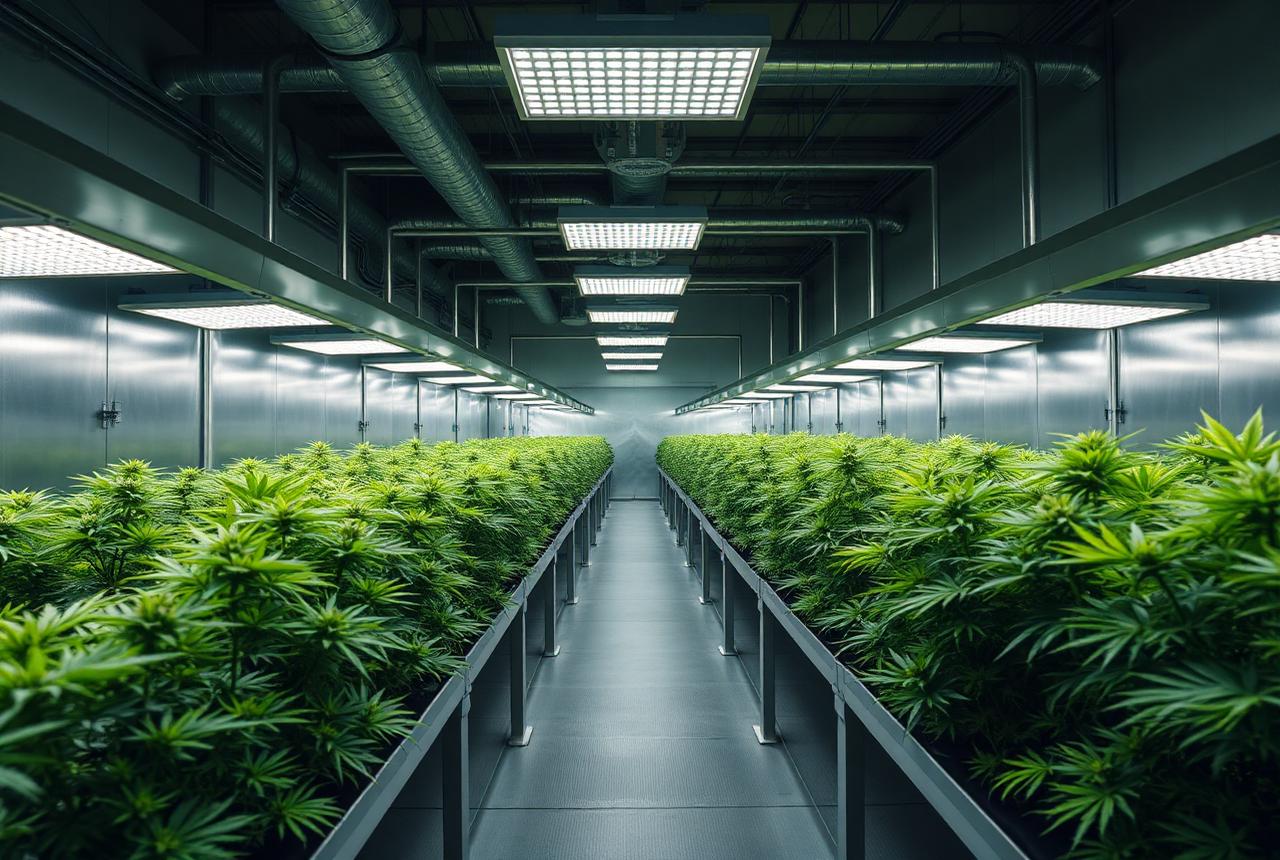
Growing is a production business with a long cycle and a biological asset. Costs accumulate for weeks before revenue exists, which makes batch-level accounting essential rather than optional.
Common Accounting Challenges
Cultivation costs are frequently expensed as incurred and never associated with the batch they produced, which leaves both the balance sheet and the cost of goods sold calculation unsupported.
- Production costs expensed instead of capitalized
- No cost per gram by room, strain, or cycle
- Waste events recorded in one system but not the other
Inventory and Cost Accounting
Immature plants, vegetative stock, drying and curing material, and finished flower are tracked as distinct inventory stages, each carrying accumulated cost through the cycle.
280E Considerations for Production
Producers generally capitalize a broader set of costs than retailers, which makes the allocation basis for shared labor, facility, and utility costs the central documentation issue.
Seed-to-Sale Reconciliation and Controls
Plant tags, harvest weights, and package identifiers should reconcile to inventory quantities, with adjustment authority limited to designated staff and every adjustment supported.
Frequently Asked Questions
- What is the most useful cultivation metric?
- Fully loaded cost per harvested gram by room and cycle. It exposes both yield problems and cost drift.
- How should utilities be allocated?
- Commonly by square footage or metered usage where available. Whatever basis is chosen should be documented and applied consistently.
- When do costs move to cost of goods sold?
- When the finished product is sold, not when it is harvested. Until then the accumulated cost remains in inventory.
Related Services
Cultivation Accounting
Cost accounting for cannabis growers: batch costing, capitalized production costs, yield analysis, and inventory reconciliation across the grow cycle.
View service Cultivation AccountingSeed-to-Sale Reconciliation
Reconciliation between the statewide seed-to-sale tracking system, inventory subledgers, and the general ledger for licensed New York cannabis operators.
View service Seed-to-Sale ReconciliationPayroll Services
Payroll processing and departmental labor allocation for licensed cannabis operators, including production labor capitalization support.
View service Payroll ServicesRelated Industries
Processors
Cost accounting and compliance support for licensed processors handling extraction, refinement, and bulk product conversion.
Explore ProcessorsManufacturers
Process costing, yield variance, and inventory accounting for licensed extraction and infused product manufacturers.
Explore ManufacturersDistributors
Wholesale accounting, receivable management, and transfer reconciliation for licensed cannabis distribution and secure transport operations.
Explore DistributorsRelated Resources
Cultivation Accounting Guide
Batch costing, capitalization, yield measurement, and inventory staging for licensed cannabis cultivation operations.
Read Cultivation Accounting GuideSeed-to-Sale Guide
How to reconcile the statewide seed-to-sale tracking system with accounting records, including variance causes, cadence, and documentation practices.
Read Seed-to-Sale GuideNew York Cannabis Accounting Guide
A 2026 technical guide to New York cannabis accounting: transaction-level cost isolation, IRC 471-11 COGS, general ledger design, a 15-day close checklist, and BioTrack reconciliation.
Read New York Cannabis Accounting GuideDiscuss Your Operation With a Cannabis Accounting Specialist
Call to talk through your license types, current records, and reporting needs, or schedule a consultation at a time that works for your team.